Last updated: November 2, 2026
Once a business owner has more than one company, money starts moving between them. One entity pays the payroll, another holds the lease, a third owns the equipment, and cash gets moved wherever it is needed that week. That is normal, and often it is exactly why the structure was set up.
The trouble shows up later. One company's books say it is owed $40,000 by its sister company. The sister company's books say it owes $31,500. Both instances are in Zoho Books, both were kept by people doing their best, and nobody can explain the $8,500.
That gap is what this post is about: why the two sides of an intercompany balance drift apart, and why it matters more at tax time than most owners expect.
What counts as an intercompany transaction
An intercompany transaction is anything of value that moves between two entities you control. Each one has to be recorded twice, once in each company's books, as two sides of the same event.
Here is what that looks like for a few common situations.
| What happened | Entity that paid or provided | Entity that received the benefit |
|---|---|---|
| One company runs payroll for staff who work for both | Records a receivable from the sister company (due from) | Records a payable to the paying company (due to) |
| A parent lends cash to a newer company | Records a loan receivable | Records a loan payable |
| A management or admin fee is charged between companies | Records fee income | Records fee expense |
| One company pays the other's vendor bill | Records a due from | Records the expense and a due to |
| A shared lease is split between entities | Records rent recovered from the other entity | Records its share of rent expense |
None of these are unusual. The problem is that every row depends on two different sets of books being updated, at the same time, for the same amount, in matching accounts.
Due to and due from: two sides of one balance
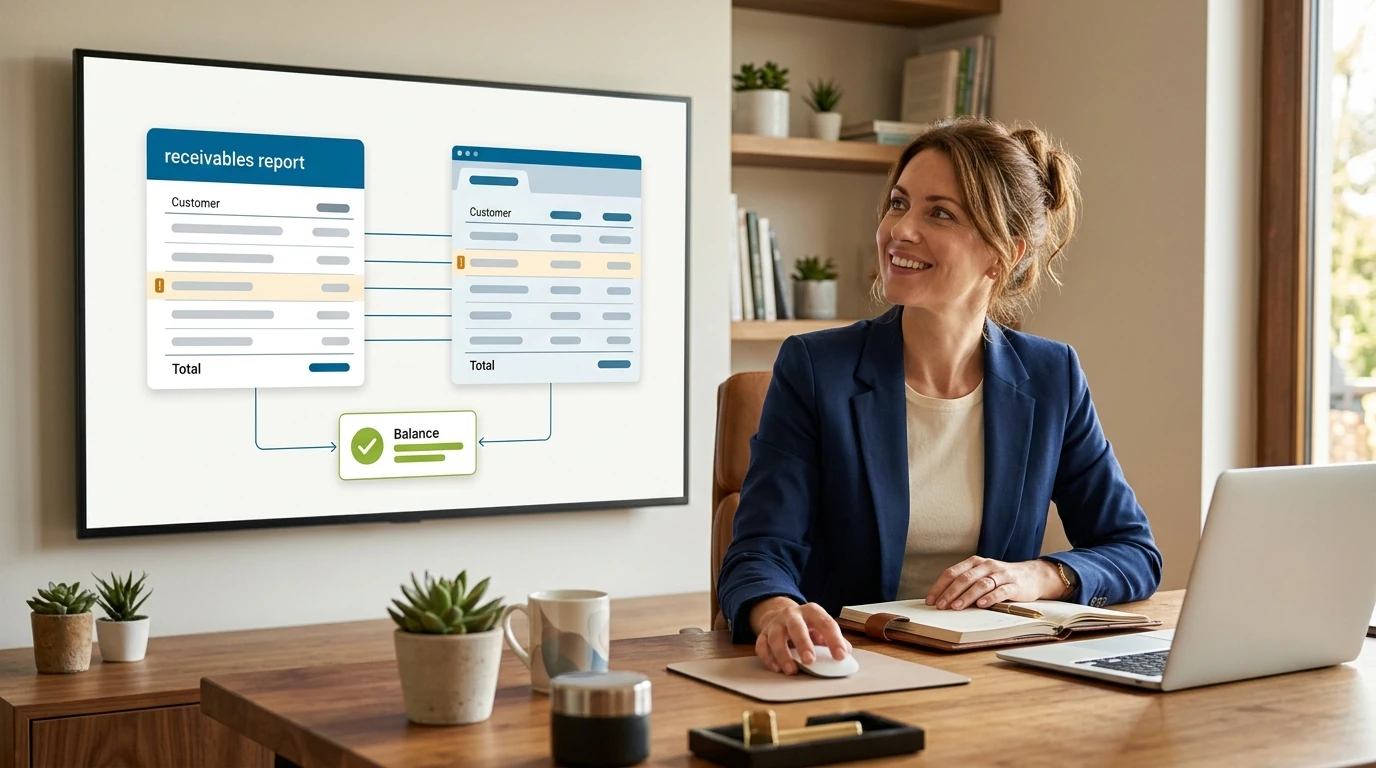
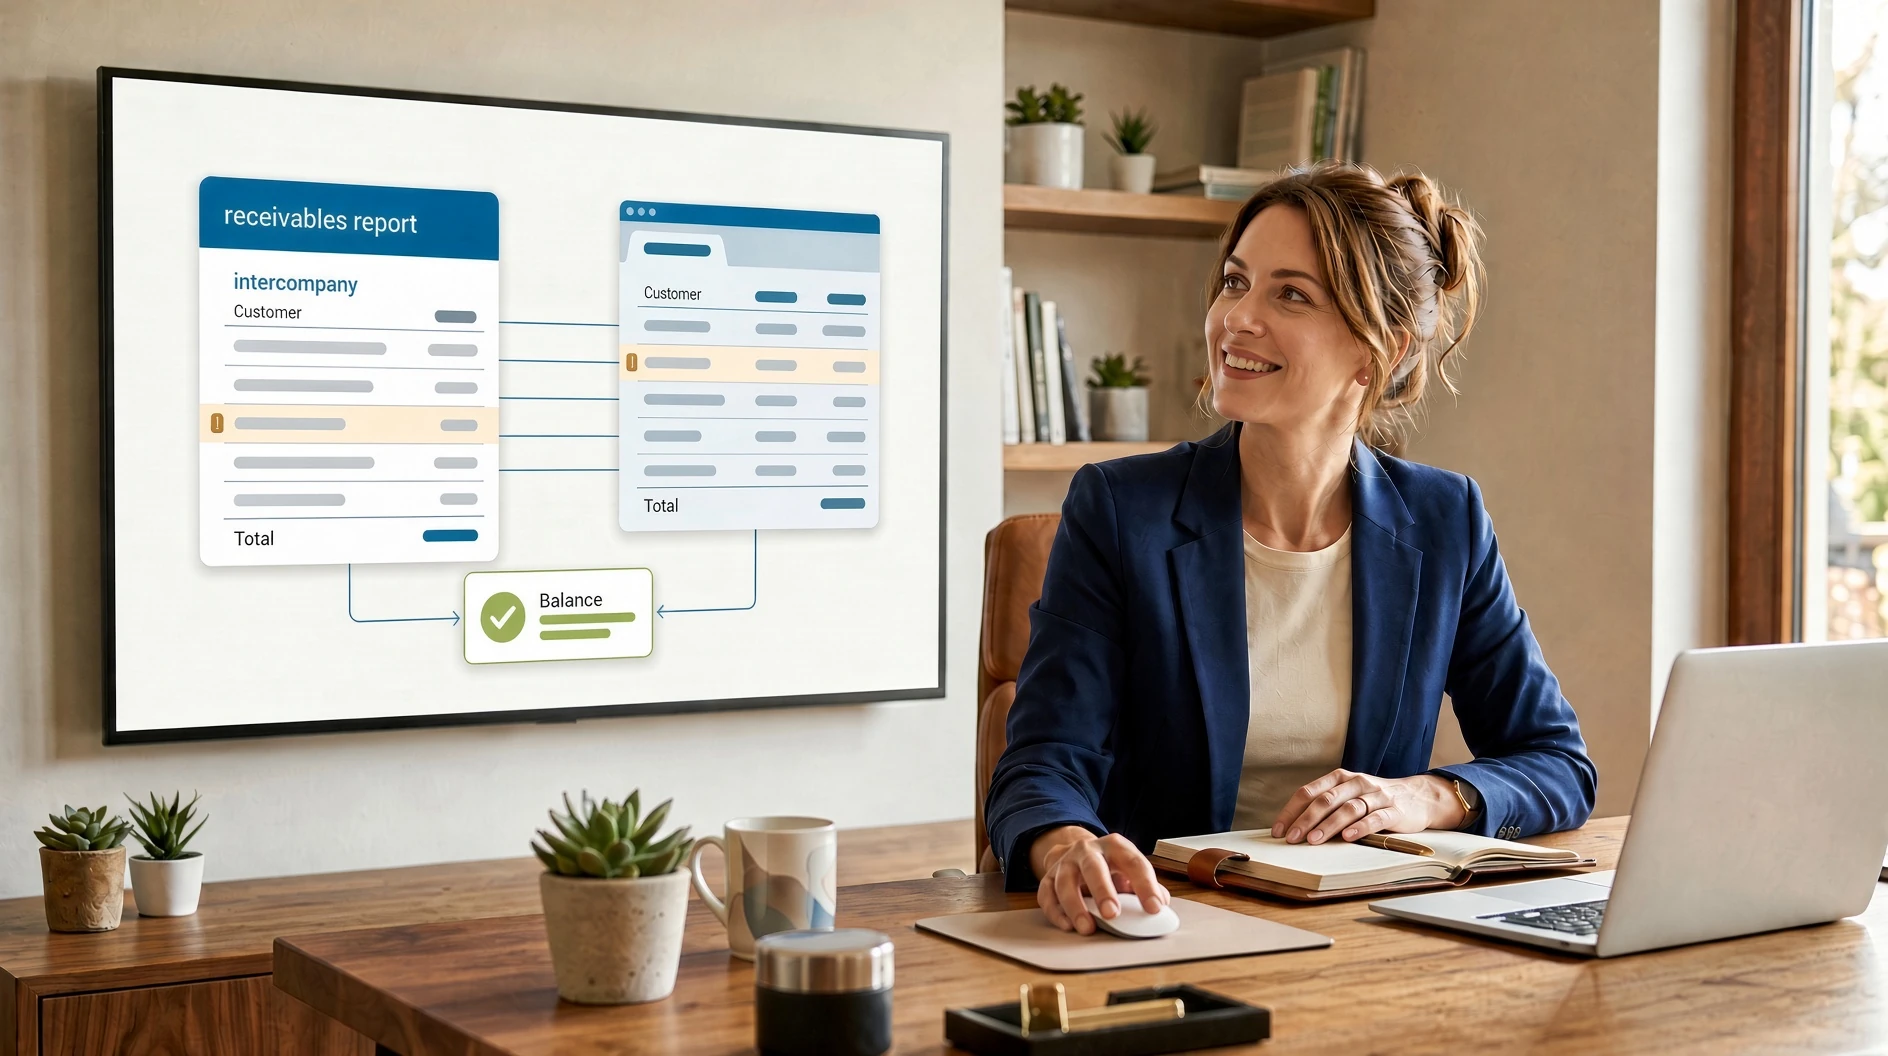
If Company A is owed money by Company B, A carries a due from B (an asset) and B carries a due to A (a liability). Those two balances describe the same relationship, so they should be equal and opposite at all times.
When they are, you can trust both balance sheets. When they are not, at least one company's books are wrong, and often both. The difference does not sit quietly either. It flows into each company's income, its equity and, eventually, its tax return.
It is the same principle behind any reconciliation: the detail on one side has to agree with the other. We wrote about the single-company version in our post on reconciling accounts receivable in Zoho Books. Intercompany is harder because the two sides live in two different instances, usually maintained by different people.
Why intercompany balances drift
We see the same handful of causes again and again in multi-entity businesses, and they rarely involve anyone being careless. They come from ordinary timing and coding decisions made one company at a time.
| Cause | What it looks like | Why it is easy to miss |
|---|---|---|
| Recorded on one side only | Company A books the charge; Company B never does | Each instance looks complete on its own |
| Recorded in different periods | A books it in March, B in April | Month-end balances disagree, then catch up, then disagree again |
| Coded to the wrong account | B records the payment as an ordinary expense instead of a due to | The P&L absorbs it and the balance sheet never shows the gap |
| Settled on one side only | Cash moves to clear the balance, but only one entity records the settlement | The balance looks paid in one instance and outstanding in the other |
| Different amounts | Fees, partial payments or rounding recorded differently | Small differences pile up over many transactions |
| Currency differences | Entities in different currencies record the same transaction at different rates | The gap looks like an accounting error but is really an exchange-rate difference |
The coding problem is the one that hurts most. When an intercompany charge gets recorded as an ordinary expense, the receiving company's profit is understated and the paying company's receivable has nothing to match against. Nobody notices until someone compares the two balance sheets side by side, and in many businesses nobody does that until the CPA asks at year-end.
For businesses with entities in more than one country, currency adds another layer of difference. That is part of why international structures need extra discipline around how each transaction is coded to its entity.
Why it matters at tax time
Each entity files its own return, or flows through to yours, based on its own books. If the intercompany balances are off, the error shows up in more than one place.
- Income lands in the wrong entity. A fee recorded on one side but not the other overstates one company's income or understates another's. With entities taxed differently, that can change the total tax bill.
- Loans can be questioned. Money moved between related companies with no paperwork and no repayment pattern may not be treated as a loan at all. Depending on the facts, it can look more like a distribution or a contribution, which carries different tax consequences.
- Charges between entities should hold up. Fees and cost-sharing between related companies should reflect a reasonable basis. A number picked to move profit from one company to another invites questions.
- Texas franchise tax can bring the entities together. Related Texas entities engaged in a unitary business may have to file a combined franchise tax report, where transactions within the group are generally eliminated. If the intercompany balances do not agree, that becomes hard to do correctly.
None of this means a multi-entity structure is a problem. It usually exists for good reasons, and it only delivers what it was meant to if the books between the entities agree. Our LLC vs. S-Corp comparison covers some of the tax thinking behind how entities are set up.
Intercompany eliminations: what they are and when you need them
If you ever need to see the group as one business, for a lender, an investor or a combined report, the transactions between your own companies have to come out. Money Company A charged Company B is not revenue to the group. It is the group paying itself. Removing those amounts so they do not inflate combined revenue, expenses, receivables and payables is called an elimination.
Eliminations only work if the two sides match. If A shows a $40,000 receivable from B and B shows a $31,500 payable to A, there is nothing clean to eliminate. The unmatched $8,500 has to be explained before any combined numbers mean anything.
That is why getting intercompany balances to agree month to month matters even if you never produce consolidated statements. Whenever someone does need the combined picture, the groundwork is already done.
When your entities live in separate Zoho Books instances
In Zoho Books, related companies are usually set up as separate organizations, each with its own chart of accounts, bank feeds and users. That separation is correct, since each entity needs its own books. It also means nothing inside the software forces the two sides of an intercompany transaction to agree. That discipline has to come from how the books are kept.
A few signs the problem has become structural rather than occasional:
- The due-to and due-from balances have not matched at any month-end anyone can remember.
- Different people keep each entity's books, and nobody compares them.
- Intercompany activity is coded differently in each organization, or to general expense accounts.
- Cash is moved between entities to "settle up" without a clear record of what is being settled.
- The difference gets larger every year, and it is the first question your CPA asks at tax time.
If several of those sound familiar, the fix usually involves going back to a point where both sides last agreed and rebuilding from there. That is the kind of work our Zoho Books cleanup is built for.
Are your entities' balances out of step?
Send us the due-to and due-from balances from each Zoho Books organization, and we will trace where they split and what it takes to bring them back into agreement.
The Bottom Line
Intercompany transactions are a normal part of running related companies. The risk is in the recording. Each one has to be recorded twice, in two different instances, and small timing and coding differences compound until the due-to and due-from balances stop describing the same relationship.
When that happens, income lands in the wrong entity, loans become harder to defend, and any combined picture of the business stops being reliable. The fix is a monthly close that treats your entities as a group, so the balances between them agree every month, not just when someone asks at year-end.
That is the work we do inside Zoho Books: closing the month for each entity and making sure what they owe each other actually ties out. You can see how we work on our Zoho Books page, and you will find us in Zoho's accountant directory.